Multivariate Normal Distribution Vs Normal Distribution Multivariate Normal Distribution Brilliant Math Science Wiki Python Visualizing A Multivariate Normal Distribution With Numpy And Multivariate Normal Distribution Probabilities YouTube Multivariate Normal Distribution Normal Distribution Is So Ubiquitous CS229a Week 9 Hackerwins Blog Upon completion of this lesson you should be able to Understand the definition of the multivariate normal distribution Compute eigenvalues and eigenvectors for a 2 2 matrix Determine the shape of the multivariate normal distribution from the eigenvalues and eigenvectors of the multivariate normal distribution
Exercise 1 Let be a multivariate normal random vector with mean and covariance matrix Prove that the random variable has a normal distribution with mean equal to and variance equal to Hint use the joint moment generating function of and its properties Solution Chap 13 Multivariate normal distributions 6 Example 2 Suppose Z 1 Z 2 Z n are independent each distributed N 0 1 De ne Z Z 1 Z n n and T X i n Z i Z 2 Show that Z has a N 0 1 n distribution independently of T which has a 2 n 1 distribution Choose the new orthonormal basis with q
CS229a Week 9 Hackerwins Blog Multivariate Normal Distribution Joint Probability Distribution Archived Post Multivariate Gaussian Distributions And Entropy 3 Multivariate Gaussian Distribution Programmathically Understanding Multivariate Gaussian Distribution Machine Learning The Normal Distribution Central Limit Theorem And Inference From A PPT II The Multivariate Normal Distribution PowerPoint Presentation Multivariate Normal Distribution And Cholesky Decomposition In Stan R How To Determine Quantiles isolines Of A Multivariate Normal
Multivariate Normal Distribution Vs Normal Distribution
 Multivariate Normal Distribution Vs Normal Distribution
https://ds055uzetaobb.cloudfront.net/brioche/uploads/4cAXDPaQsy-2varnormal.png?width=1200
The multivariate normal distribution is a generalization of the familiar univariate normal or Gaussian distribution Hogg et al 2005 Miller and Miller 1999 to p 2 dimensions
Pre-crafted templates provide a time-saving option for producing a varied series of files and files. These pre-designed formats and designs can be utilized for various individual and professional tasks, consisting of resumes, invites, leaflets, newsletters, reports, presentations, and more, improving the material development procedure.
Multivariate Normal Distribution Vs Normal Distribution
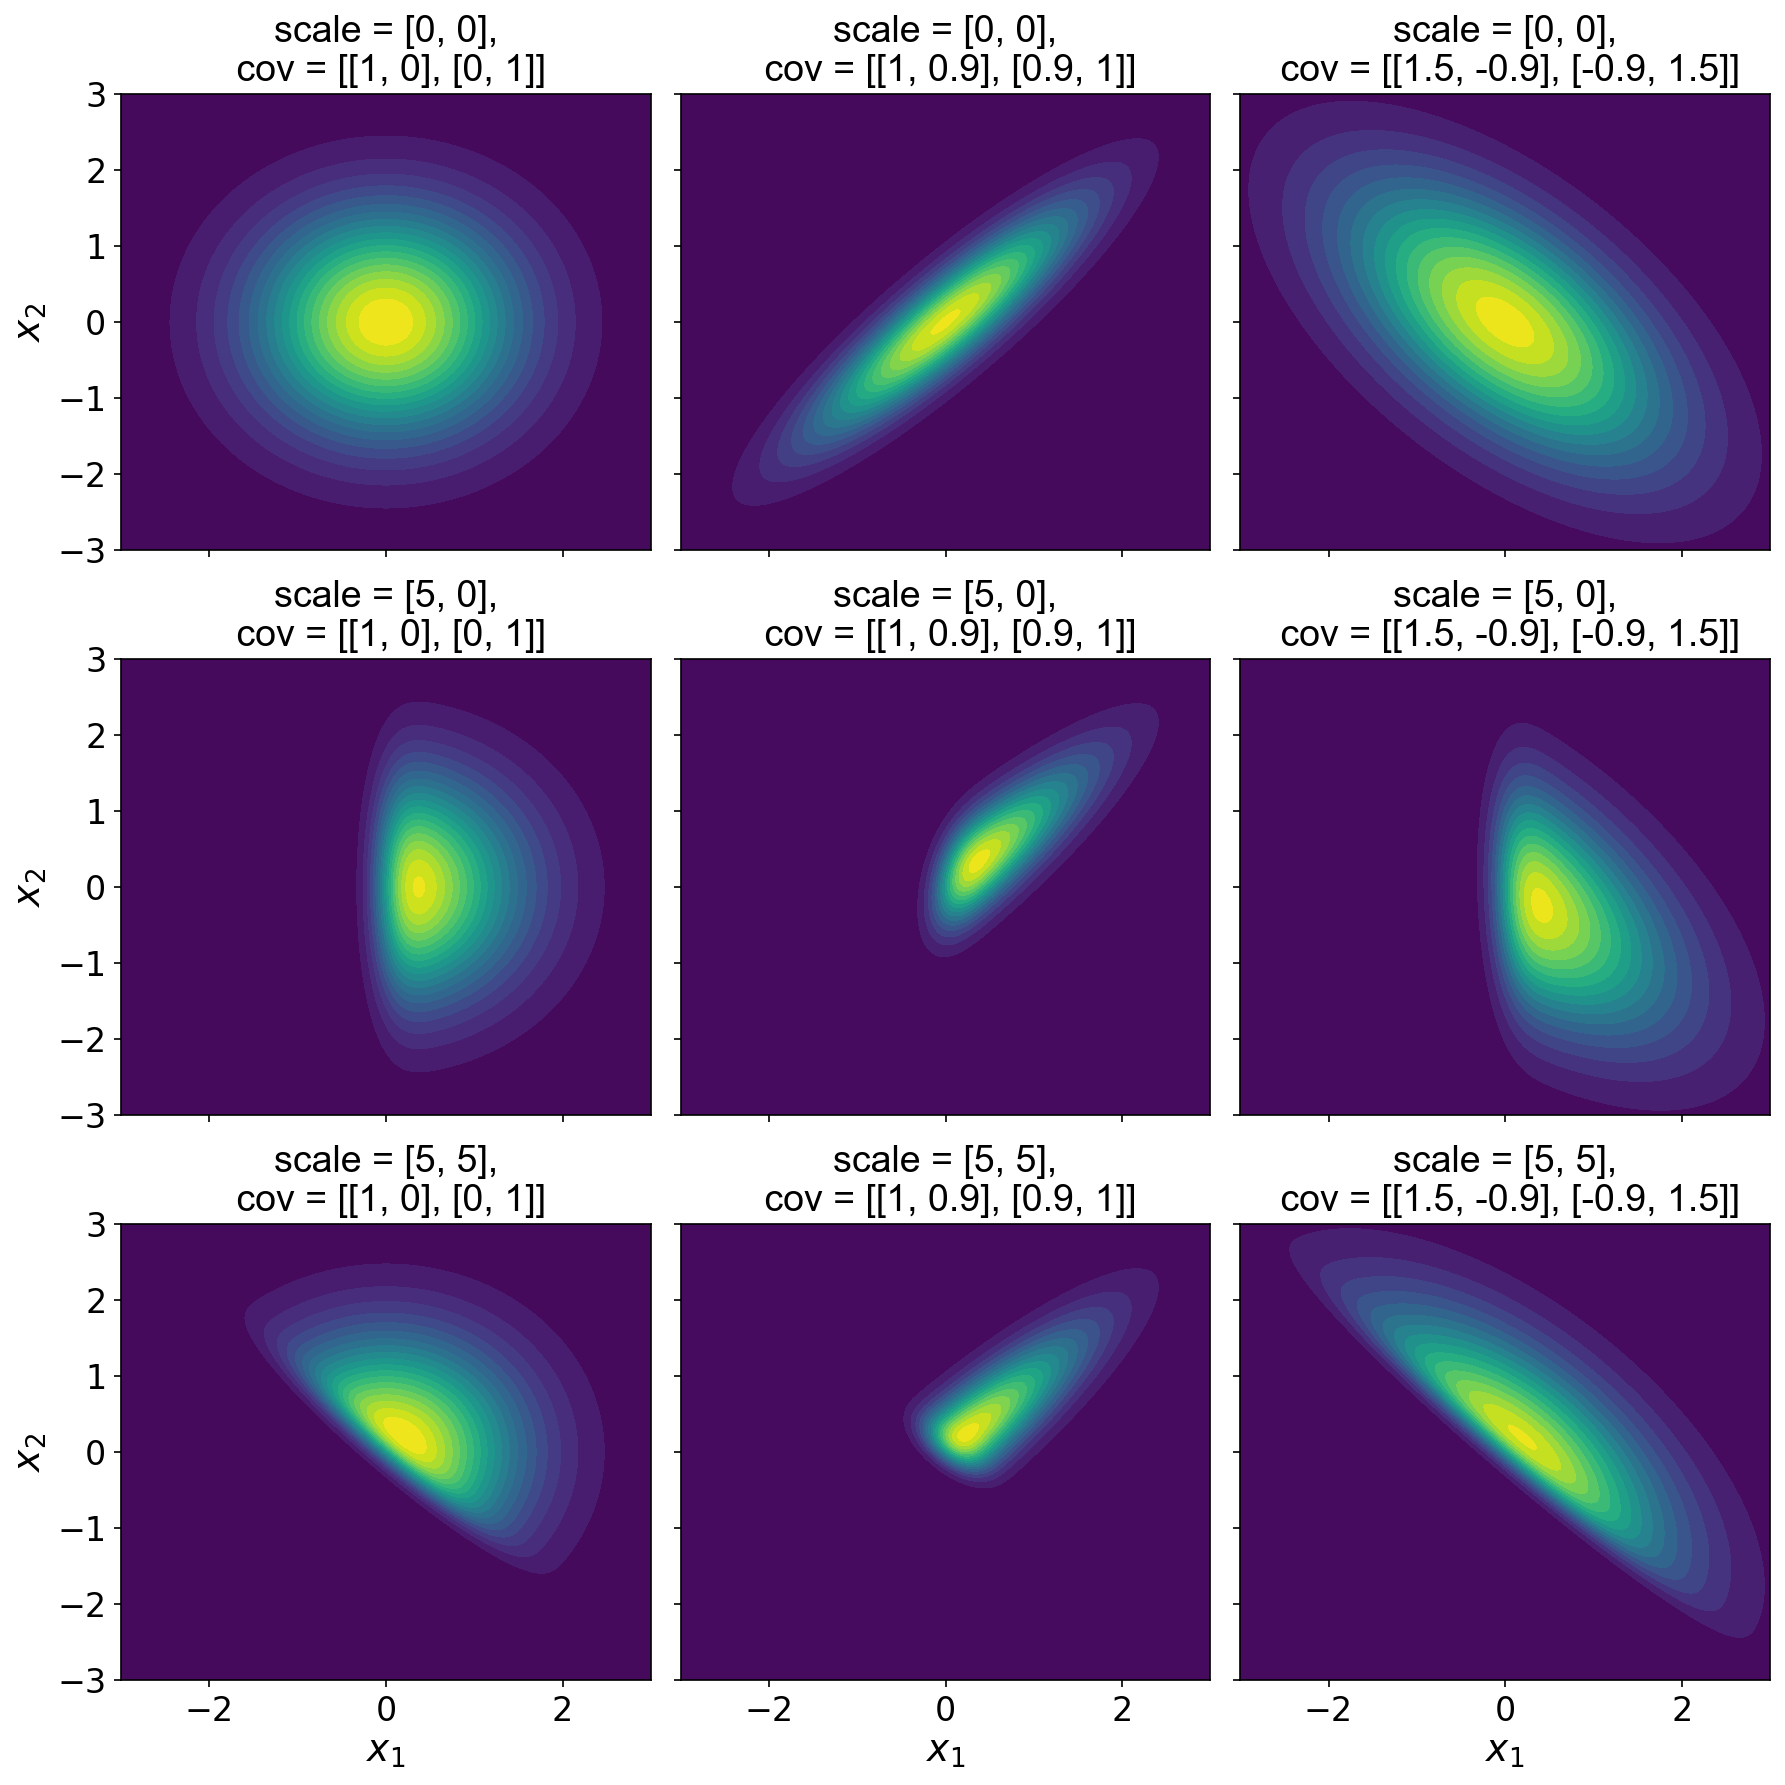
A Python Implementation Of The Multivariate Skew Normal
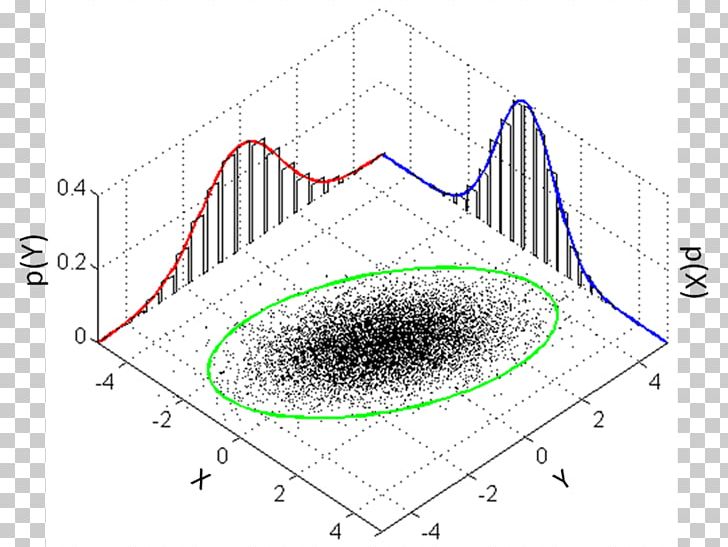
Multivariate Normal Distribution Joint Probability Distribution

Archived Post Multivariate Gaussian Distributions And Entropy 3
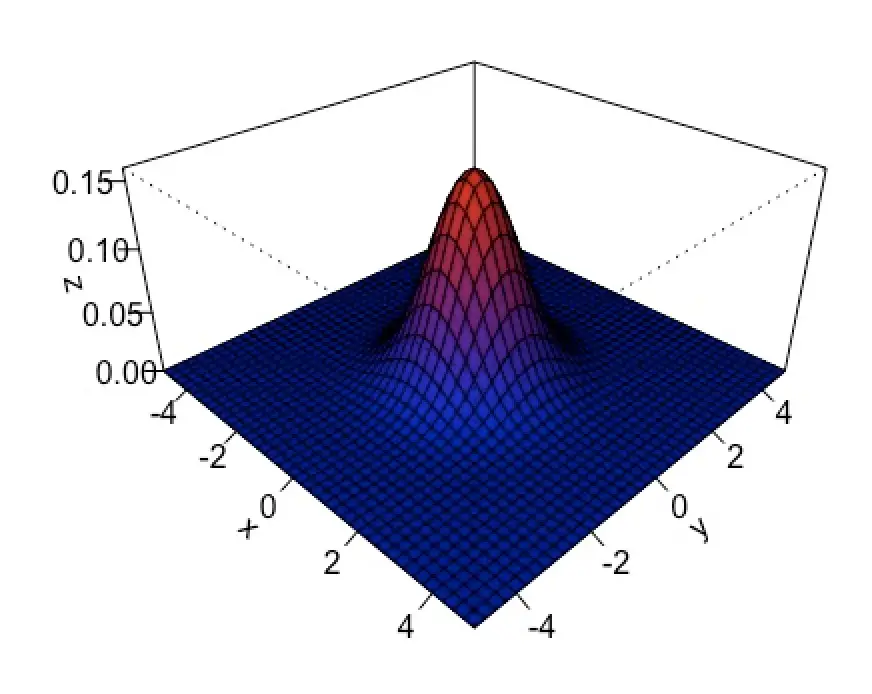
Multivariate Gaussian Distribution Programmathically
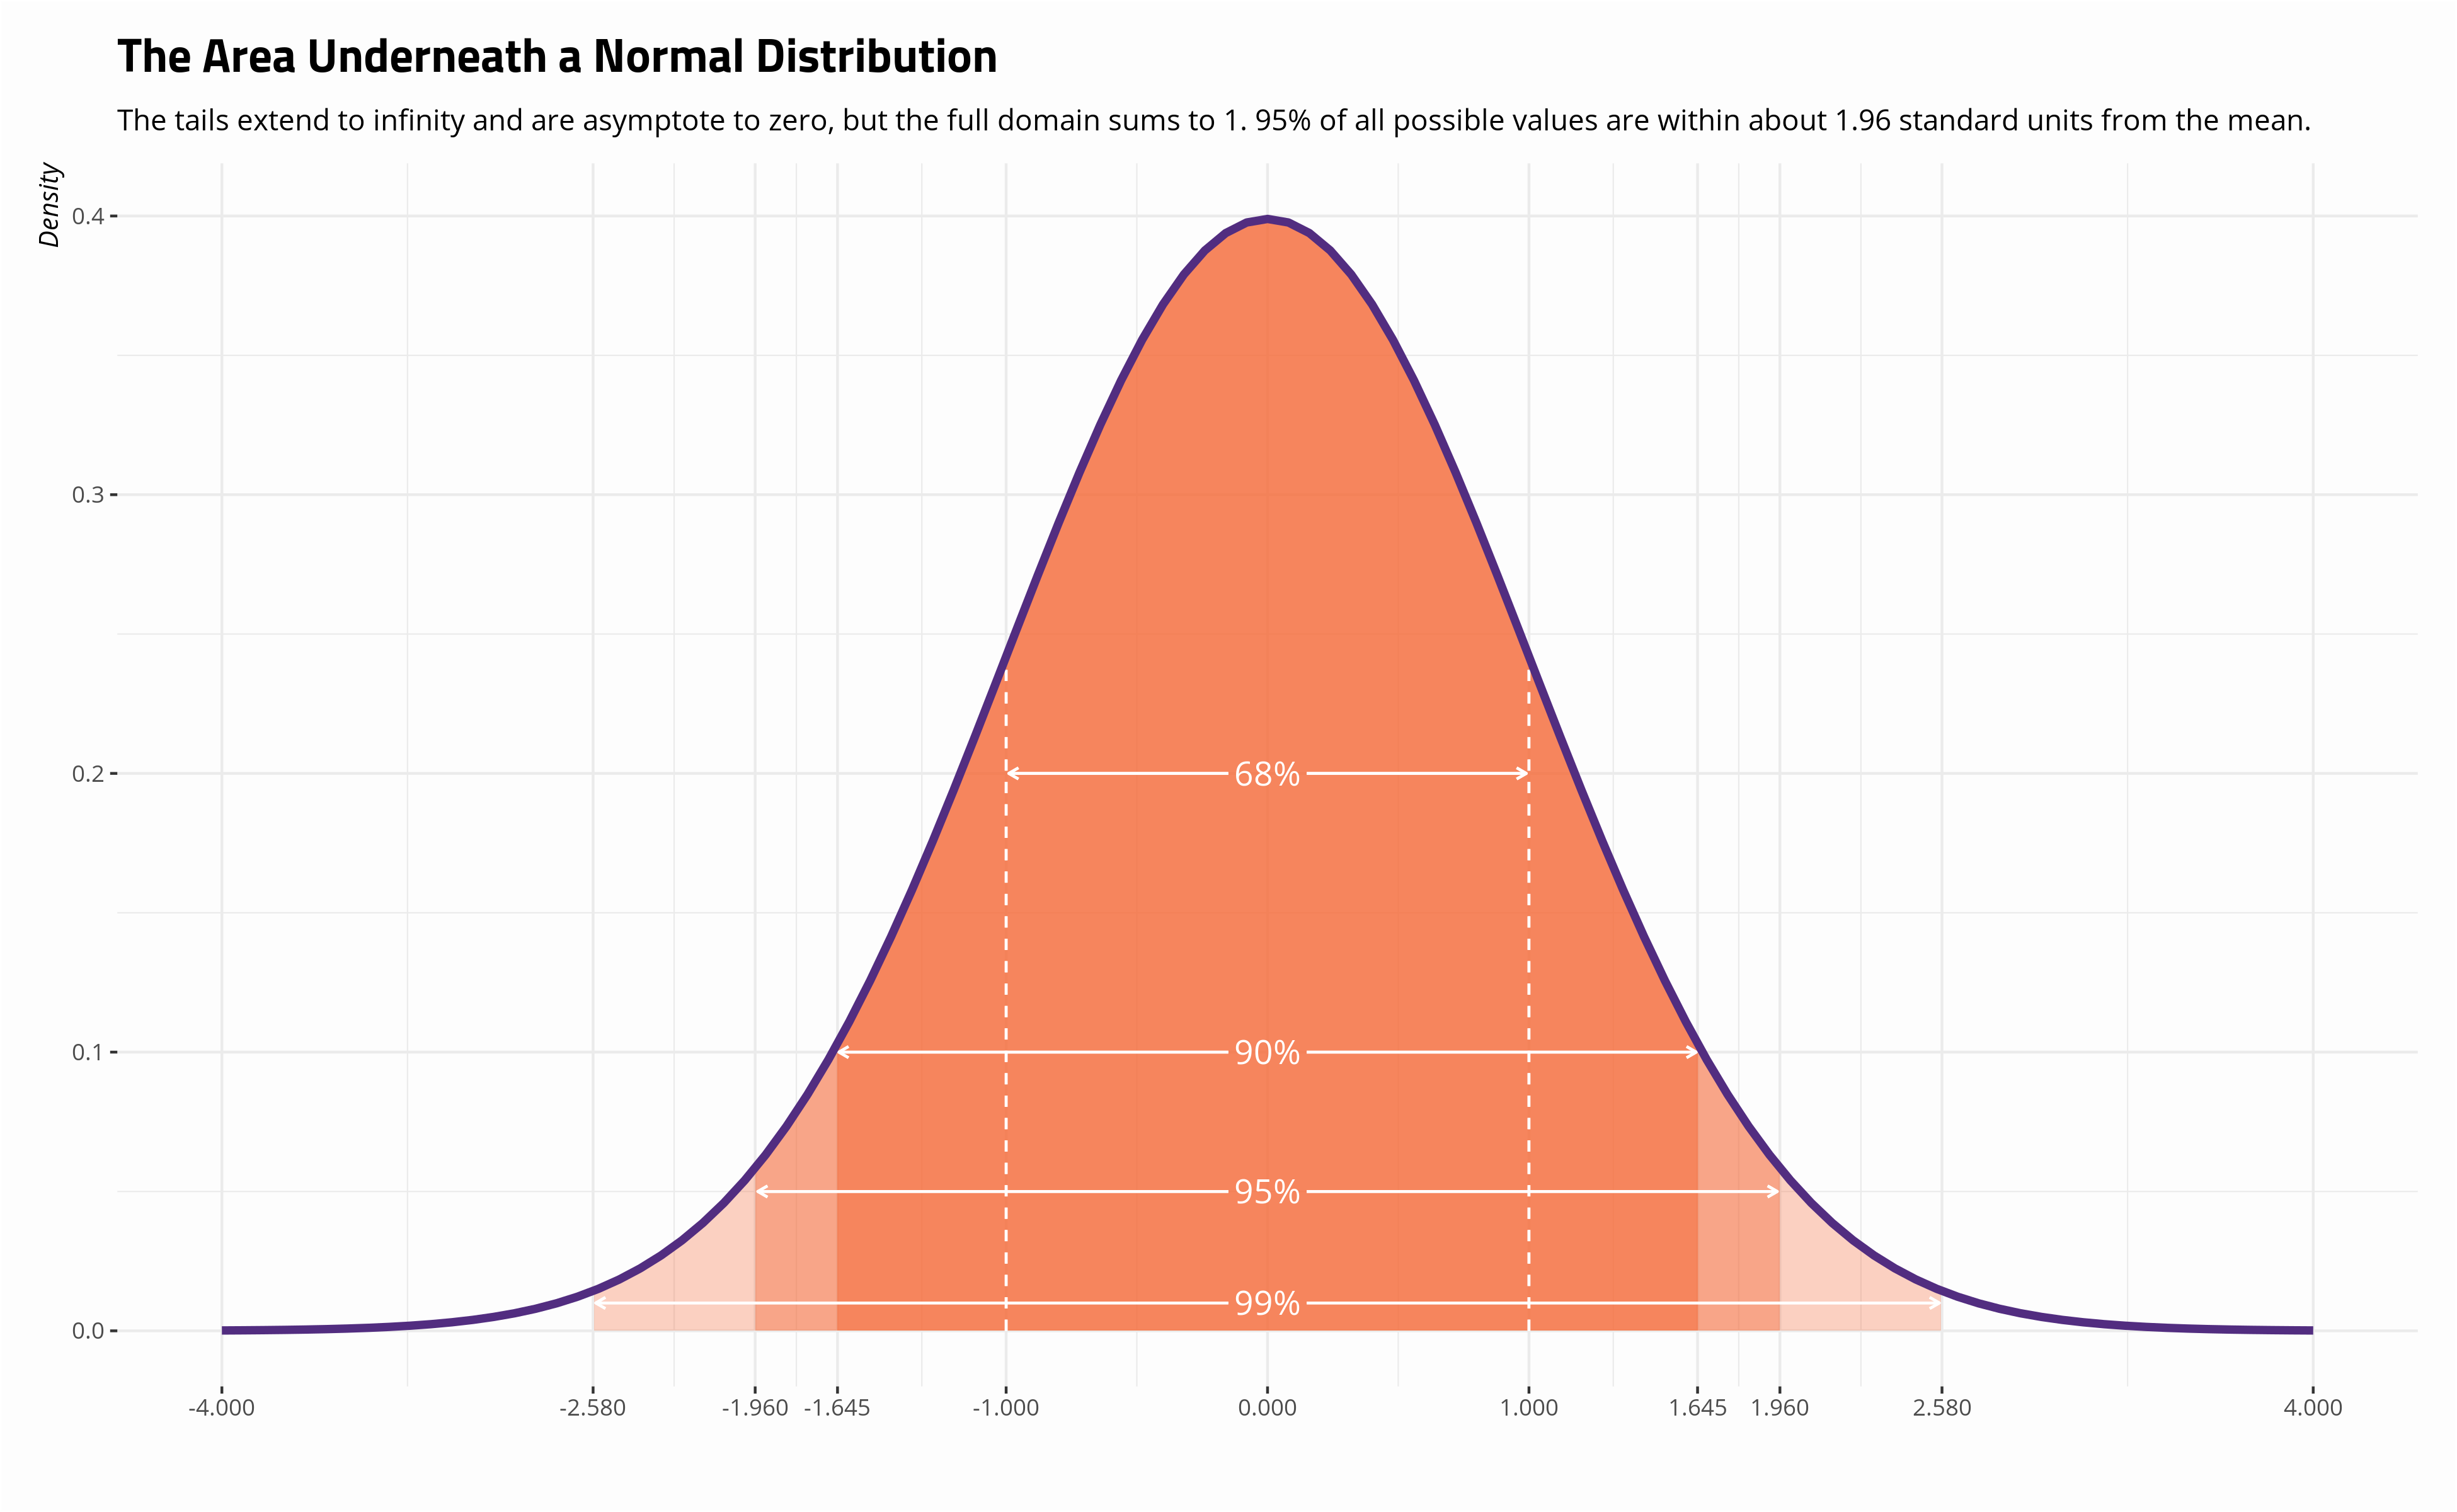
The Normal Distribution Central Limit Theorem And Inference From A

PPT II The Multivariate Normal Distribution PowerPoint Presentation

Understand the definition of the multivariate normal distribution Compute eigenvalues and eigenvectors for a 2 2 matrix Determine the shape of the multivariate normal distribution from the eigenvalues and eigenvectors of the multivariate normal distribution 4 1 Comparing Distribution Types 4 1 Comparing Distribution Types

Multivariate Normal Distributions If we have a p x 1 random vector X that is distributed according to a multivariate normal distribution with a population mean vector and population variance covariance matrix then this random vector X will have the joint density function as shown in the expression below

The graph of f can be understood by means of the level curves The probability density function 2 of the standard bivariate normal distribution is given by 2 z w 1 2 e 1 2 z2 w2 z w R2 The level curves of 2 are circles centered at the origin The mode of the distribution is 0 0 2 is concave downward on z w

A multivariate normal distribution is a vector in multiple normally distributed variables such that any linear combination of the variables is also normally distributed

Has a multivariate Normal distribution Proof We need to show that for any constant vector w the linear combination w X n wiXi has a Normal distribution But since the Xi s are independent Normals the i 1 wiXi s are also independent Normals so by the Proposition their sum is a Normal random variable
The conjugate prior for the mean term of a multivariate normal distribution is a multivariate normal distribution p jX p p Xj 11 where p is a multivariate normal distribution N 0 0 The implication of this prior is that the mean term has a Gaussian distribution across the space that it might lie in generally large values of 0 I would be careful to say a joint distribution is synonymous with a multivariate distribution For example a joint normal distribution can be a multivariate normal distribution or a product of univariate normal distributions A univariate normal distribution has a scalar mean and a scalar variance so for the univariate one dimensional random
Abstract Multivariate normal distribution is the natural extension of the bivariate normal to the case of several jointly distributed random variables Dating back to the works of Galton Karl Pearson Edgeworth and later Ronald Fisher the multivariate normal distribution has occupied the central place in modeling jointly distributed